Herndon split in two this fall — detached held its value and its premium while the attached market filled with record inventory and sellers began paying buyers to close. Here’s what it means if you’re buying or selling.
Data Sources: BrightMLS (closed sales & inventory) · Freddie Mac (mortgage rates) · Hud’s Compass proprietary behavioral market intelligence.
This October, Herndon’s housing market pulled in two directions at once. Detached homes held their value — the resale median rose 9.2% for the year — and the well-shown house still cleared in about two weeks. But underneath, only 20 detached homes traded, the fewest in the eleven-year record, while the attached market — townhomes and condominiums — filled with the most inventory it has ever carried against the thinnest demand on record.
The sticker prices mostly held. What moved was the premium buyers paid and the terms sellers accepted. In October, 59% of Herndon townhome sellers — and half of detached sellers — paid the buyer money at closing. The discount didn’t show up on the price tag; it moved to the premium and the settlement table.
If you’re a buyer in the attached market, that’s the clearest opening in a decade. If you’re a seller, it’s the difference between the home that sells and the one that sits.
How many homes are selling in Herndon right now?
The metric, plainly: Forget the price for a moment — the honest read on demand is the contract ratio: for every home sitting on the market, how many just went under contract. Above about 1.0, buyers compete and the seller names the terms. Drop well below 1.0 and it flips to the buyer.
What Herndon did: Herndon’s demand split by tier this year. Detached firmed, from 0.49 to 0.59. But the attached market collapsed — townhome fell from 0.73 to 0.33 and condominium from 0.37 to just 0.08, both the lowest October readings in the eleven-year record. That condo reading is barely one home going under contract for every thirteen listed.
What it means: Detached demand held, but in the attached tiers fewer buyers are chasing each home than at any point in over a decade — the mechanical reason leverage has swung hard to the buyer on townhomes and condos. It shows up next as record inventory, more time, and real negotiating room.
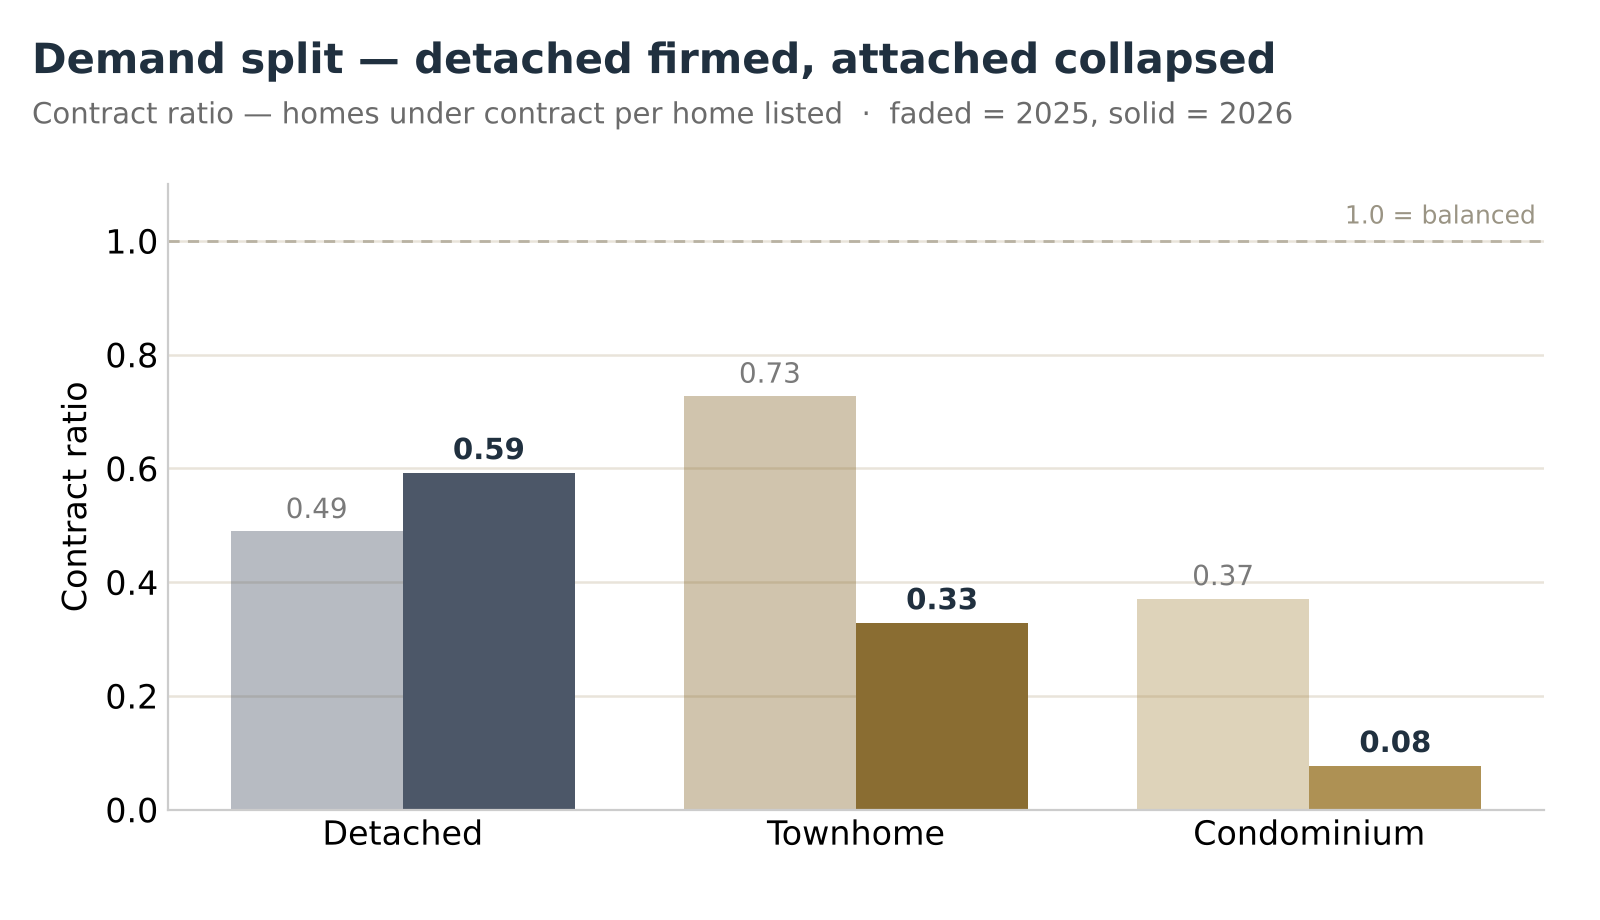
Herndon Contract Ratio by structure, a year ago vs. now. Source: BrightMLS.
Is there more inventory in Herndon? (Yes — a record)
The metric, plainly: Months of supply answers a simple question: at today’s pace of sales, how long until every listed home is gone? Under about three months is tight to balanced; climb above it and buyers finally have room.
What Herndon did: The attached market filled fast. Townhome active inventory jumped 76% in a year to 58 — the most in the eleven-year record — pushing months of supply to 2.42, also a record. Condominium supply reached 4.22 months, the highest in the ten-year record, even though inventory rose only 11% — because almost nothing sold. Detached stayed tight at 1.32 months. One caveat: about one in six townhome listings is new construction marketed before it’s finished; strip that out and the resale inventory a buyer can move into is closer to 2.0 months.
What it means: For the first time in years, attached-home buyers in Herndon have the two things that create negotiating power — choice and time.
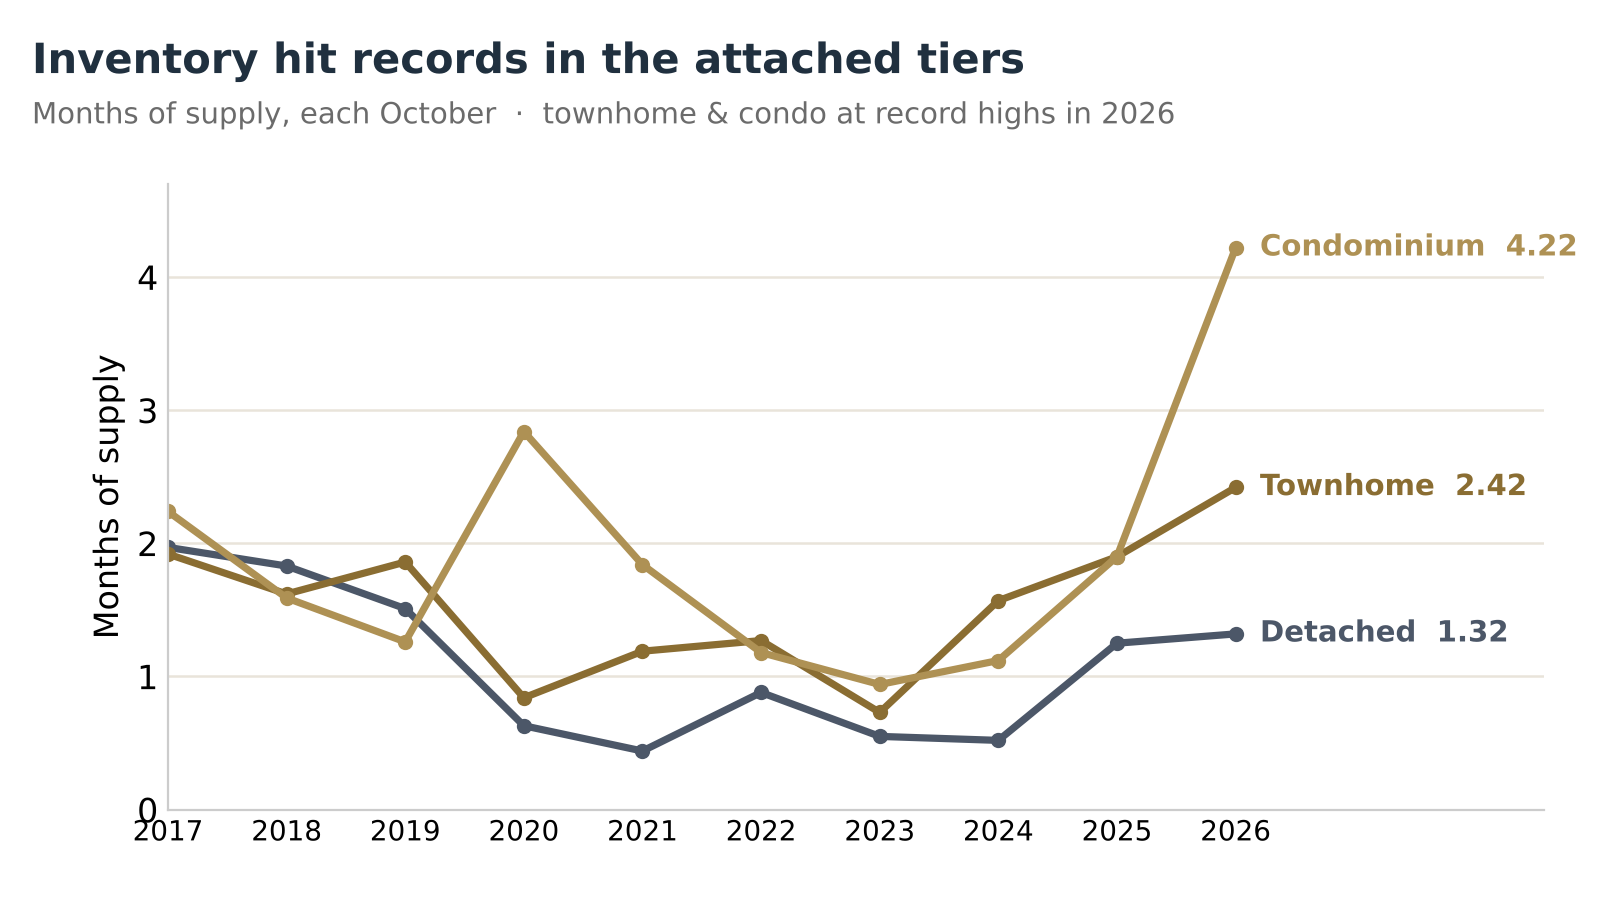
Herndon Months of Supply by structure, each October through 2026. Source: BrightMLS.
Are Herndon home prices falling?
The metric, plainly: A single month’s median lurches around for a dumb reason — whether big or small homes happened to sell. That’s a mix, not a trend. The honest view is the multi-year line: is the price still climbing?
What Herndon did: Over the decade the three structures separate cleanly. Detached has climbed the whole way and is still climbing — up 2.4% this year, with the October resale median at $926,000. Townhomes plateaued and eased slightly, holding near $593,000 resale. Condominiums eased to about $335,000. The single-month attached prints look worse — a townhome −15.7%, a condo −8.1% — but both are thin, new-construction-skewed months; the year is the honest read.
What it means: This is not a market where values collapsed — detached is appreciating and the attached tiers eased only modestly. So if the price mostly held, where did the softness go? Into the two places a median can never show you: the premium buyers will pay, and the terms sellers accept. The next two sections are each one of those.
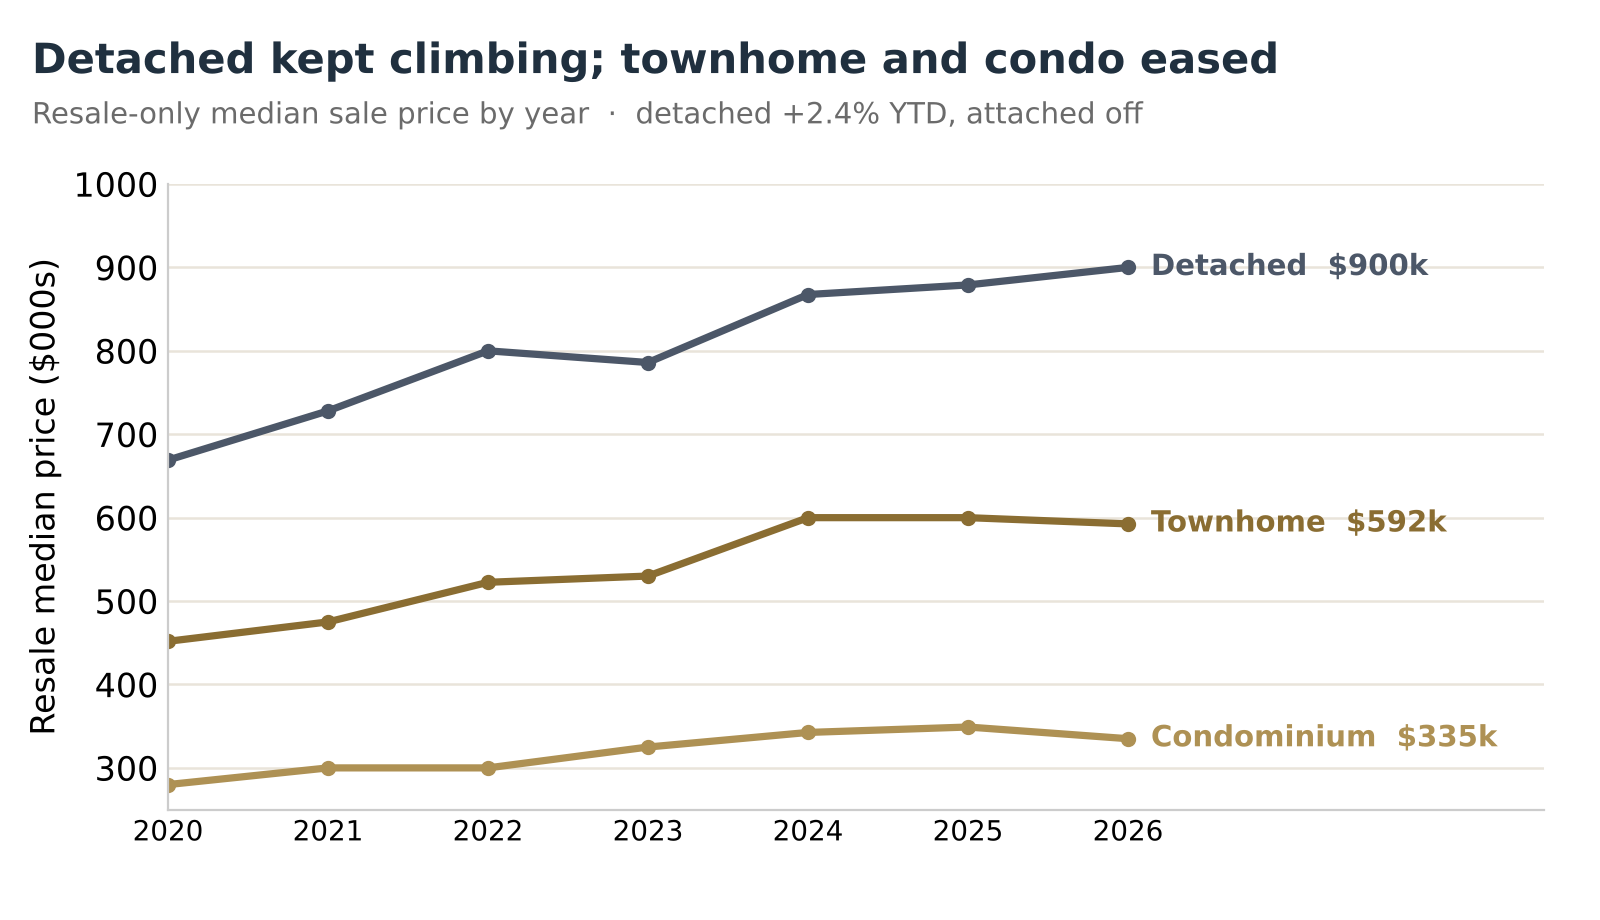
Herndon resale median sale price by structure, 2020-2026. Source: BrightMLS.
How do we read the Herndon market?
The metric, plainly: Here’s the lens no other agent will hand you. Everyone quotes a price; we quote a premium — what a buyer paid over the county’s own assessed value of the home. Read it the way a trader reads a stock against its book value: the county already set the book, so the premium is pure market conviction, and it doesn’t care whether the house is 1,200 feet or 4,000. It answers the only question a buyer has — am I overpaying? — and its mirror for the seller — am I getting full value?
What Herndon did: This October, Herndon detached still carried real conviction, trading about 11 points above assessed. Townhomes drew just +2; condominiums landed at the county’s number, with no premium left at all. Watch it move through the year and you can see conviction drain out of the attached market while detached holds its ground — the condo tier even dipped below assessed in late summer:
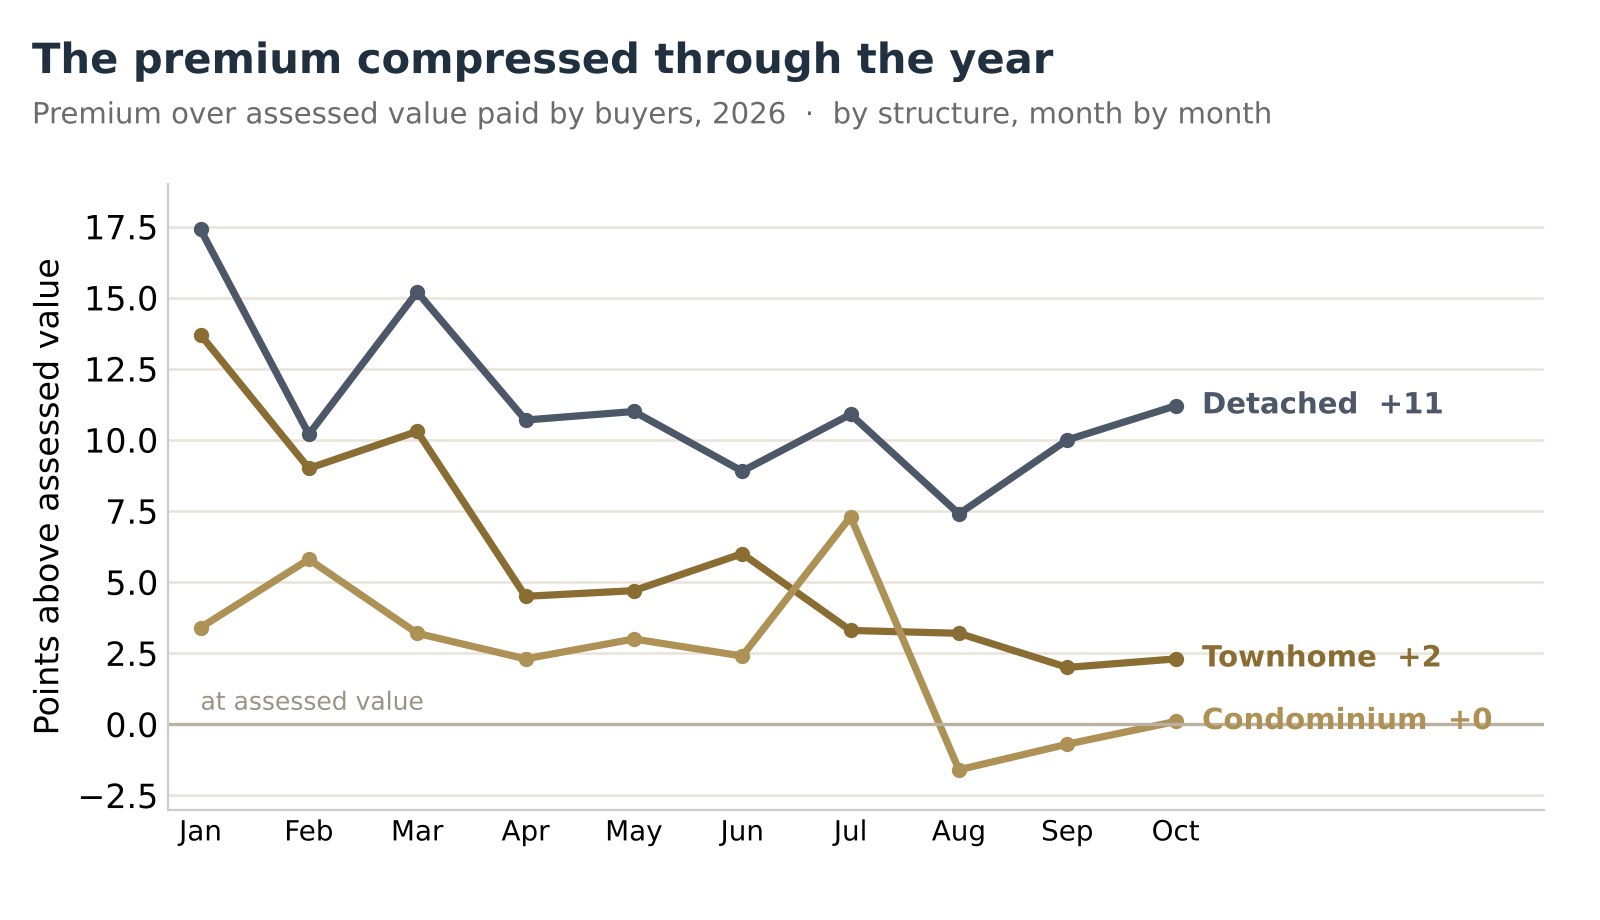
Herndon premium over assessed value paid by buyers, by structure, through 2026. Source: BrightMLS.
Now hold this October against last. Detached gave back the least — +13 a year ago, +11 now. Townhomes lost five, from +7 to +2. And condominiums are the whole story: from +8 to zero, the entire premium gone in twelve months. Here’s what the consumer never sees — the sign prices barely moved, so the median looks calm, but the premium collapsed, because pricing power softens here first, a year before the median flinches.
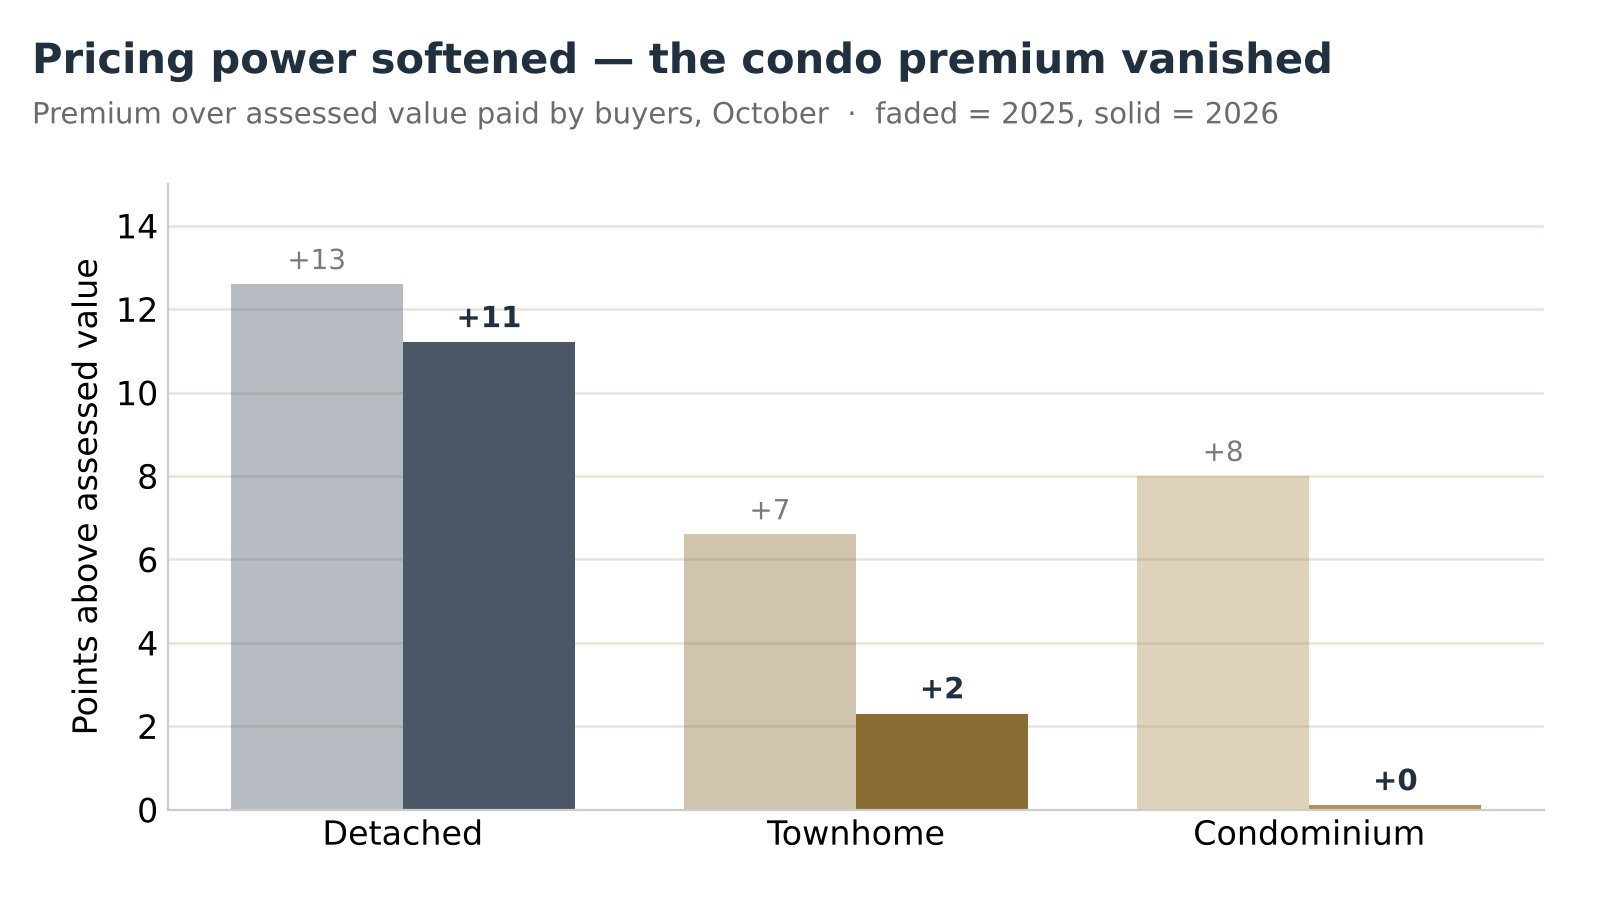
Herndon premium over assessed value paid by buyers, a year ago vs. now. Source: BrightMLS.
What it means — and what to do: This is Buffett made literal: be greedy when others are fearful, because the fear is already on the tape. If you’re buying attached in Herndon, you’re stepping in after the premium reset to the county’s number — most of the drop everyone’s bracing for has already happened. That’s not a falling knife; it’s the discount. If you’re selling, stop anchoring to last spring’s premium; it’s gone. Price to the conviction buyers are paying this month and you close while the neighbor still chasing it keeps cutting. No one else on the corridor is even reading this number — which is exactly why it’s your edge.
Why are Herndon sellers paying concessions?
The metric, plainly: A seller concession is cash the seller hands the buyer at closing — for closing costs, a repair, or the most powerful use of all, buying down the mortgage rate — instead of cutting the asking price. Watch the rate it happens, not the dollar figure: when more sellers pay but the price holds, the real discount has moved off the sign and onto the settlement sheet.
What Herndon did: It set records. 58.8% of townhome sales carried a concession (median $12,895, about 2.1% of price) — the highest in seven years, up from 18.8% a year ago. Detached hit 50.0%, condominium 45.5%. The sticker prices held; sellers paid, at the table, to get the deal closed.
The math, on a Herndon townhome: Rates ran a full point higher this year — about 6.25% a year ago to roughly 7.3% now — and that didn’t kill demand, it rate-gated it: the buyers are still here, they’ve just lost purchasing power. Which is the opening. A dollar at the closing table does far more as a rate buy-down — permanent until you refinance — than as a price cut. Take a $600,000 townhome, 10% down, a $540,000 loan on a 30-year fixed:
| The deal | Monthly payment (P&I) | You save |
|---|---|---|
| Pay full price, 7.25% | $3,684 | — |
| $10,000 off the price, 7.25% | $3,623 | $61 / mo |
| ~$10,800 concession → rate bought to 6.75% | $3,503 | $181 / mo |
| Same money. The buy-down saves about three times the monthly — and it’s permanent until you refinance, roughly ~$7,200 more in your pocket over five years. | ||
Illustrative; P&I only, excludes PMI. A buy-down runs about one point (roughly 1% of the loan) per quarter-percent and varies by lender and the day’s pricing.
What it means — the buyer’s play: High rates don’t feel like opportunity, but in a market this thin they are. Thin demand is exactly what hands you the leverage to make the seller buy your rate down. Stack the savvy-buyer move on top — buy closer to assessed value, add a little sweat equity — and you build equity faster and shed PMI sooner. The same lever that priced others out is the one that prices you in. That’s being greedy when others are fearful.
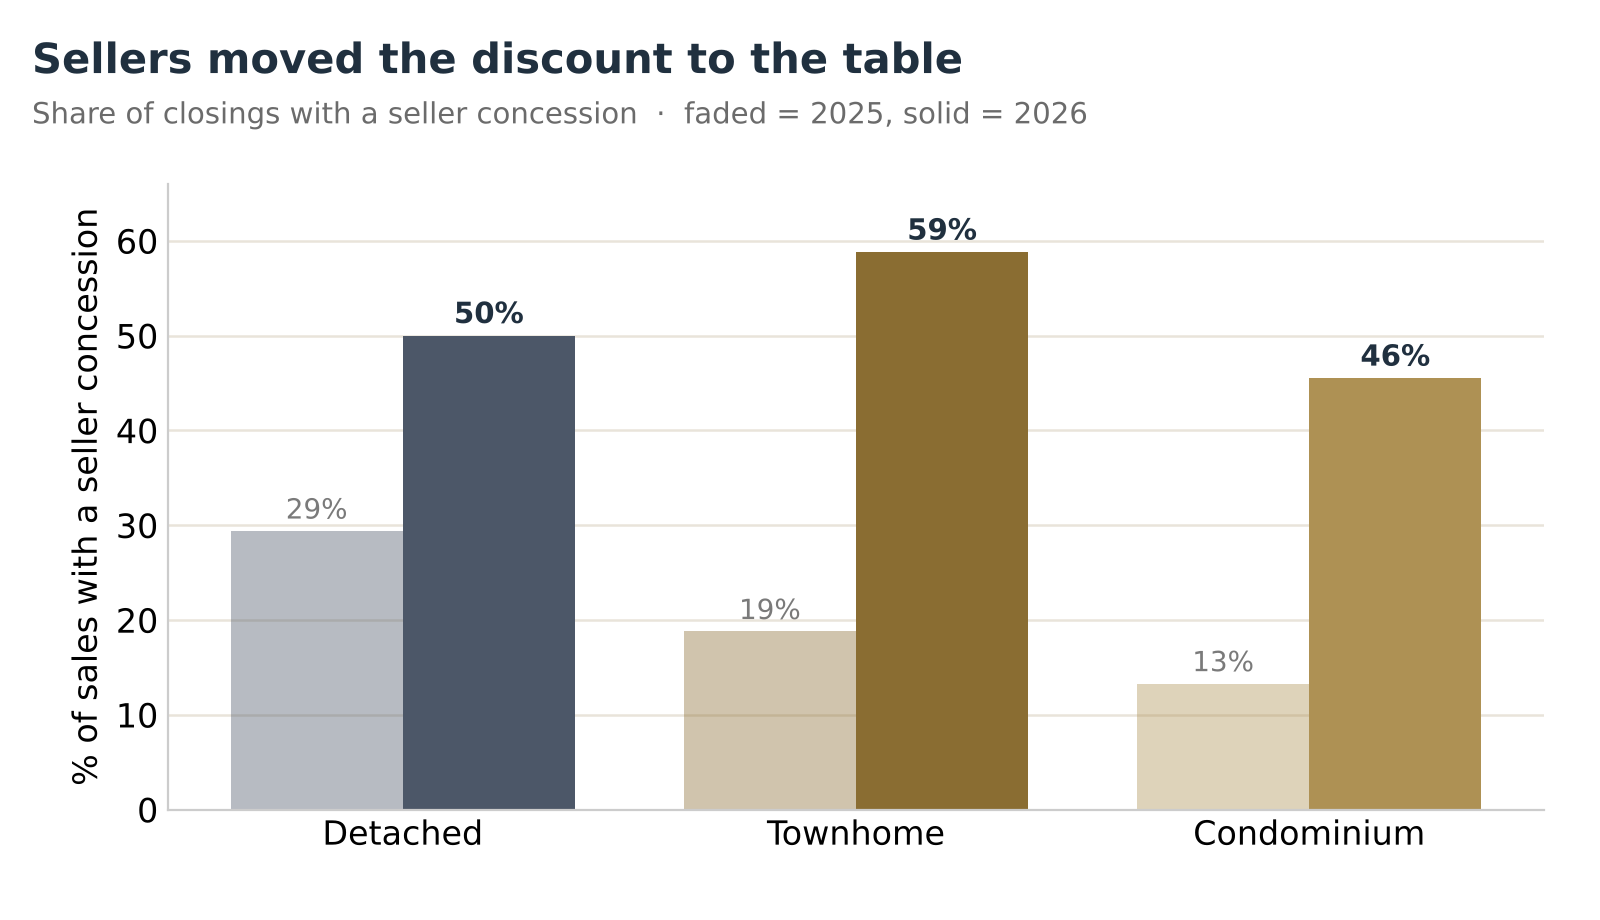
Herndon seller-concession frequency by structure, a year ago vs. now. Source: BrightMLS.
What should you do in Herndon right now?
If you’re selling a detached home: You’re in the strongest position in town — value held and even rose. Price to today’s market and show it well; the clean home still clears in about two weeks. Build a concession into your plan — half of October’s detached buyers received one — and offering it up front can be the difference between the home that sells and the one that sits in a record-thin market.
If you’re selling a townhome or condo: You’re competing against the most inventory the tier has ever carried, so condition and price do all the work. Price to the most recent comparable sales — not last spring’s — show the home spotless, and expect to offer a concession; well over half your competition already is. The turnkey, realistically priced home still sells; the one that reaches sits.
If you’re buying in Herndon — especially a townhome or condo: This is the clearest opening in a decade. You have choice, time, and leverage on both price and terms — and a premium that has already reset to the county’s number. Don’t just negotiate the number — negotiate a concession and ask your lender to apply it as a rate buy-down.
If you’re buying detached: Your leverage is thinner — value is still climbing and the right home moves fast — so the room is in the terms, not the price. Be ready to move decisively on the clean one, and ask for help at closing.
The bigger picture: This isn’t only a Herndon story. October was the month the whole county turned — across Fairfax, inventory rose and demand fell in every structure at once, and townhome and condo contract ratios hit eleven-year lows countywide. Herndon’s version is sharper: it’s where the corridor’s supply wave crested. Herndon isn’t a weak market — it’s a divergent one, and knowing which side of it your home sits on is the whole game.
HUDS COMPASS
NORTHERN VIRGINIA’S
ONLY MARKET INTELLIGENCE INDEX
Conditions data tells you what is coming — supply, demand, the direction of pressure. Anyone with an MLS login can pull it. The Compass tells you why — it reads the behavior behind the closings, scoring four needles from every closed sale. And the read tells you how to act. This month’s Herndon report reads the closed side: detached held its value while the attached market’s premium gave and condo demand hit an eleven-year low — the discount didn’t show up on the sign, it showed up at the table.
One teaching point unlocks the rest. Most people watch sale-to-list price — but a list price is just an asking number a seller can type at will. Watch sale-to-assessed instead: the county’s assessed value is a fixed anchor that doesn’t move with a seller’s optimism. When a home clears above assessed with no concession, real demand paid up. When it holds its list price but closes with money back at the table, the asking number was a wish the terms quietly corrected.
Common Questions
Is Herndon a buyer’s or seller’s market right now? Both, depending on what you own. Detached is still a seller’s market — tight supply, value rising, clean homes clearing in about two weeks. Townhomes and condominiums have turned hard to the buyer: record inventory, demand at eleven-year lows, and real room to negotiate.
Are Herndon home prices dropping in 2026? Mostly no. Detached value is up 2.4% for the year with an October resale median near $926,000, townhomes held near $593,000, and condominiums eased to about $335,000. The single-month attached prints look worse on thin, new-construction-skewed volume; what really softened is the premium buyers pay over assessed value and the terms sellers accept.
What is the median home price in Herndon right now? It depends on the structure, which is why one blended “Herndon median” misleads. In October, detached ran about $926,000, townhomes about $593,000, and condominiums about $335,000. A detached buyer and a condo buyer are shopping two different markets.
How much are Herndon homes selling over assessed value? This is the number no other agent hands you. In October, detached traded about 11 points over the county’s assessed value, townhomes +2, and condominiums right at the county’s number — down from roughly +13, +7, and +8 a year ago. The condominium tier handed back its entire premium in twelve months, and that premium moves before the median ever does.
What is a seller concession, and what’s a rate buy-down? A concession is money the seller credits the buyer at closing. Applied as a rate buy-down, that money permanently lowers your mortgage rate — which cuts your monthly payment far more than taking the same amount off the price. In October, 58.8% of Herndon townhome sales carried a concession, a seven-year high.
Is now a good time to buy in Herndon? In the attached market, the leverage buyers have now — choice, time, negotiable terms, and a condo premium already reset to the county’s number — is the strongest in years. Waiting for lower rates often means competing against more buyers when they fall. The move is to negotiate today’s price and terms, not to wait.
Is now a good time to sell in Herndon? Yes — if it’s priced to this market rather than last spring’s. Detached still holds its value and its premium and clears in about two weeks. Attached sellers face record inventory and a premium that has reset, so accurate pricing and a built-in concession strategy matter more than they did a year ago.
How fast are homes selling in Herndon? The well-shown detached home still clears in about two weeks; townhomes and condominiums take longer as inventory has climbed to eleven-year highs — the condo tier is the slowest, clearing in roughly seven to eight weeks. Speed now depends far more on pricing and structure than it did a year ago.
Want to know which side of this market your home is on?
Every home tells a story the county numbers can’t. If you’re weighing a move in Herndon — buying or selling — let’s read your home’s numbers together and build the strategy around them.
Michele Hudnall
Real Estate of Northern Virginia | Equity-First Real Estate Strategy
Life Long Northern Virginia Native | 25-Year Reston Resident | HOA Board President, Whitney Park East | South Lakes Drive
[email protected] | 703.867.3436 | RealEstateofNVA.com | @realestateofnva
I help Northern Virginia buyers and sellers make smarter decisions with local market analysis, strategic guidance, and real-world context, not hype headlines.
Disclosure: Michele Hudnall is a licensed real estate agent in Virginia. This post represents her personal analysis and good-faith opinion as a Reston resident and does not constitute legal or financial advice. Full disclosure at RealEstateofNVA.com. All analysis and opinion are my own and based upon local, real-time data. Please consult with a financial or legal professional as required.
Privacy Statement | Disclosure Notice